

Aspire Account Center
Atlanticus Services
- 3.3
- 966.00 Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
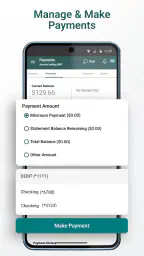
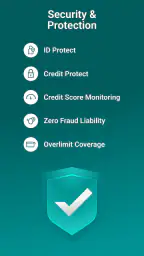
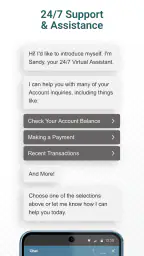
Aspire Account Center Pros and Cons
Pros
- Centralizes account details, settings, and support in one app.
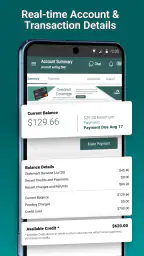
- Makes it easier to monitor balances and recent account activity.
- Provides quick access to Aspire’s customer service channels.
- Useful notifications can help users stay informed about account updates.
- Clean layout makes common account tasks relatively easy to find.
Cons
- Some features may depend on the user’s Aspire account type or region.
- Requires a stable internet connection for most account functions.
- Users may need to complete extra verification during sensitive actions.
- Occasional app updates may change menu locations or available features.
- Limited usefulness for people who do not already use Aspire services.
 Analysis by All-app
Managing a credit card from a phone sounds simple until an important payment is due, a transaction looks unfamiliar, or you need to check your available credit while away from home. I spent time looking at Aspire Account Center as a finance app built around that narrow but useful job: keeping an Aspire credit card account within reach instead of relying on a desktop browser or paper statements. My overall impression is practical rather than exciting. It is a focused account-management tool, and that focus can be helpful for people who want fewer distractions, but it also means it should not be mistaken for a complete budgeting or money-management suite.
The app is free, aimed at Everyone, and comes from Atlanticus Services. It has passed the half-million-install mark and holds an average rating of 3.3 from roughly 2.1 thousand ratings. Those figures suggest a real user base, but also a mixed experience. I would approach it as a companion for an Aspire card, not as a replacement for a bank’s full mobile app. The most important question is whether you value quick access to card information more than a broad collection of financial tools.
How the account experience feels in everyday use
The first strength is its clear purpose. When I open a dedicated card-management app, I expect to find account information, payment-related tasks, and transaction checking without having to navigate through savings, investments, transfers, or other products. Aspire Account Center is best understood in that way. Its role is to put the credit card account in one place and make routine checking possible from a phone.
That narrow scope can make the experience easier to understand for someone who does not want a complicated financial dashboard. A person checking whether a recent purchase has appeared, reviewing the balance before making another purchase, or dealing with a payment deadline can start from the same account center. I find that more approachable than opening a general finance app and searching for the correct card among several accounts.
At the same time, the app’s usefulness depends heavily on the user already having an Aspire credit card relationship. It is not the right choice for someone looking for a general-purpose budgeting app, a bill organizer for several lenders, or a single place to combine checking, savings, loans, and cards from different providers. Those users will usually be better served by a broader financial app or by their main bank’s application.
Readability and navigation for routine tasks
For a finance app, readability matters more than visual novelty. Numbers such as balances, available credit, payment amounts, and transaction values need to be easy to distinguish at a glance. My preference is for a screen that supports a quick check without forcing me to interpret decorative charts or promotional panels first. A dedicated account center has an advantage here because its information architecture can stay close to the card itself.
I also think about navigation in terms of stress. When a user notices a purchase they do not recognize, they should not have to explore several unrelated sections before reaching the transaction history. Likewise, someone who is trying to make a payment late in the evening benefits from a direct path rather than a confusing sequence of menus. The app’s focused identity gives it a reasonable foundation for these situations, even though the quality of the experience will still depend on the phone, connection, and account state.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
One useful habit is to treat the first account check after signing in as a verification step, not merely a glance at the balance. I would look at the latest activity, compare it with receipts or notifications, and then check the amount available for future spending. This workflow catches two different problems: a potentially unfamiliar transaction and the risk of assuming that the balance alone tells the whole story.
The current version is 4.22.47-6102, and the app supports devices running Android 6.0 or later. That broad operating-system reach may help people using older Android phones, particularly those who do not replace devices frequently. However, an older supported operating system does not automatically mean every person will find the interface comfortable. Screen size, display scaling, font settings, touch response, and the phone’s own accessibility tools can change the experience considerably.
Motor and sensory considerations
Finance tasks often involve careful tapping rather than fast interaction. A user may need to select a payment option, enter an amount, review a confirmation screen, or inspect a transaction. That makes large, well-separated controls especially valuable for people with tremors, limited dexterity, or difficulty with precise touch gestures. I would take a moment to increase the phone’s text size or display size before judging the app, then check whether important labels remain visible and whether controls still fit comfortably on screen.
There is a trade-off here. Enlarging text can improve reading but may also cause crowded layouts or require more scrolling. Smaller displays can make that tension more noticeable. For a user with low vision, the practical test is not simply whether text can be enlarged; it is whether the balance and payment information remain understandable after enlargement. I would avoid making a financial decision from a cramped screen and use a larger device when a detailed review is necessary.
People who rely on screen readers should also evaluate the app through their normal Android accessibility setup before depending on it for time-sensitive account work. Labels, reading order, focus behavior, and the way amounts are announced all matter. I cannot treat the presence of an accessibility setting on the phone as proof that every part of a third-party app will behave perfectly. My advice is to try a low-risk task first, such as reviewing an old transaction, before using the app for an urgent payment.
Sensory comfort includes more than vision. Some users need low-distraction screens, predictable movement, or a quiet process that does not demand rapid decisions. A focused card app is potentially easier to manage than a broad financial dashboard filled with unrelated information. On the other hand, if a user finds account alerts, contrast, or screen changes difficult to interpret, the safest approach is to combine the app with a personal routine: review the amount slowly, confirm the intended action, and save any confirmation information in a format that is easy to revisit.
Situational access: when the phone becomes the practical option
The strongest use case is a small, ordinary moment. Imagine I am standing in a shop and want to know whether a purchase will fit within my available credit. I do not need a budget forecast or an investment overview; I need a quick account check. A dedicated card center is more suitable for that moment than signing in to a desktop site, provided I can use the phone comfortably and have a dependable connection.
Another scenario is travel. A person may want to review recent card activity from a hotel room, check an account after an unfamiliar notification, or confirm that a payment-related action was recorded. Having the account center on the phone can reduce dependence on a laptop. I would still avoid treating mobile access as a substitute for careful security habits. A shared device, an unlocked screen, or a rushed glance in a public place can expose sensitive financial information even when the app itself is working as intended.
The app can also support users whose schedules make traditional account management inconvenient. Someone working irregular hours, caring for another person, or dealing with limited transportation may value the ability to check the card from home or during a short break. This is where situational accessibility becomes meaningful: the benefit is not a special feature but the reduced need to reach a branch, find a computer, or wait for a more convenient time.
There are limits to phone-based access. Poor reception, a nearly empty battery, a damaged screen, or difficulty authenticating can turn a convenient tool into a frustrating one. I would not wait until a payment deadline or a suspected problem to discover that the app is difficult for me to operate. A better routine is to sign in during a calm moment, learn where the essential account information appears, and keep an alternative method available for situations in which the phone is not usable.
Useful workflows beyond simply checking a balance
One non-obvious benefit of a dedicated account center is that it can encourage more frequent, smaller reviews. Instead of waiting for a monthly statement, I can check activity after a few meaningful purchases. That makes it easier to spot a mistaken amount while the receipt is still nearby. It also helps separate two concerns that people often mix together: what has posted to the account and what I remember spending.
A second useful workflow is preparing before making a payment. I would first inspect recent activity, then review the amount I intend to pay, and only afterward complete the payment process. This order reduces the chance of acting on an outdated assumption. It is a simple discipline, but a mobile account center makes it easier because the information is available at the moment I am ready to act.
A third trade-off involves using this app alongside, rather than instead of, a personal budget. The account center can help me see what happened on the card, but it does not automatically become a complete picture of household finances. If I use several cards or pay expenses from different accounts, I still need a separate method for comparing income, recurring bills, and spending categories. The focused design is a strength for card administration and a weakness for wider financial planning.
I would also use the app as a checkpoint before contacting support. Reviewing the latest activity and account information first can help me describe the issue more clearly if I do need assistance. That will not solve every problem inside the app, but it can prevent a vague conversation about “something being wrong” when the real issue is a specific transaction, balance change, or payment status.
Remaining barriers and reasons to choose another option
The mixed average rating is a reminder not to assume that a focused purpose guarantees a smooth experience. Account apps are judged during high-pressure moments, and even a small sign-in problem or unclear status message can feel serious when money is involved. I would be cautious about relying on any mobile application as the only way to manage a credit card until I had personally tested the tasks I use most.
Another barrier is the difference between access and understanding. Showing a balance is not the same as explaining why it changed, whether a transaction is still pending, or how a payment affects the account. Users who need detailed financial education, debt-planning tools, or a unified view of multiple institutions may find the app too limited. In those cases, a broader budgeting service or the main banking app may offer better context, even if it is less direct for Aspire card tasks.
People with accessibility needs should make their own practical test rather than relying on general claims. Try signing in, moving through the account information, reading a transaction, and reaching the payment area using the phone’s preferred settings. If any step requires precise tapping, tiny text, or visual interpretation that is difficult, the app may not be the best sole channel. A larger screen, device accessibility features, or an alternative account-management method may be safer.
Privacy and security also deserve everyday attention. I would use a personal device, keep the operating system maintained, avoid discussing account details in public, and lock the phone when I am finished. These are not reasons to reject the app; they are part of using a mobile finance tool responsibly. Convenience becomes less valuable if it encourages rushed checks or casual exposure of account information.
Who should use it and who should skip it
I would recommend Aspire Account Center to an Aspire cardholder who wants a straightforward way to review and manage that card from an Android phone. It is especially suitable for someone who prefers a dedicated account space, checks transactions regularly, and values mobile access during ordinary situations such as shopping, commuting, or traveling. The Everyone content rating also makes it broadly positioned for general users rather than a narrowly age-specific audience.
I would suggest skipping it as a primary financial tool if you need one dashboard for several banks, detailed spending categories, shared household budgeting, investment tracking, or extensive planning features. It is also not ideal for someone who cannot comfortably read or operate the app on their current device and has no dependable alternative. In that situation, the right answer may be a different access method rather than another attempt to force a phone-based workflow.
The app is free to download, which removes a financial barrier to trying it. I would still judge it by reliability and clarity, not by price alone. A free app that saves time on routine card checks can be worthwhile, while a free app that leaves me uncertain about an important action is not enough for high-stakes use.
My inclusive verdict
After looking at the app through the needs of different users and situations, I see Aspire Account Center as a useful but specialized companion. Its best quality is focus: Aspire card information is more approachable when it is not buried inside a much larger financial system. That can support quick checks, calmer routines, and access when a computer is inconvenient.
Its limitations are equally important. A focused card center cannot replace a complete budget, and mobile convenience does not guarantee comfortable access for people with low vision, motor difficulties, sensory sensitivities, or unreliable phone conditions. I would test the essential tasks with personal accessibility settings enabled, use a slower review routine for payments, and keep an alternative way to manage the account.
My recommendation is therefore conditional but positive. If you already use an Aspire credit card and want a free, dedicated Android account tool, it is worth trying. If you need broad financial planning or highly predictable accessibility across every interaction, compare it with the tools you already trust before making it your only option. The app does one kind of job well in principle: bringing card management closer to the moments when you actually need it. For me, its value comes from focused access, not from trying to be an entire financial life in one app.
Frequently Asked Questions
What is Aspire Account Center used for?
Aspire Account Center is designed to give users a central place to manage their Aspire-related account information and services. Depending on the account type and region, you may be able to review account details, monitor activity, access statements or documents, update personal information, and find support resources. Available features can vary, so the app may not provide the same tools for every user.
Who can use Aspire Account Center, and how do I sign in?
The app is generally intended for existing Aspire customers or authorized users with eligible accounts. Sign-in normally requires the credentials connected to your Aspire account, and some users may need to complete an additional verification step. Before downloading, make sure your account is supported in your country and that the email address or phone number registered with Aspire is still accessible for login recovery.
Is Aspire Account Center safe for managing account information?
Aspire Account Center is intended for handling personal and account-related information, so users should treat it like any financial or customer-service application. Use the official Android or iOS store listing, keep the app updated, avoid signing in over unsecured public networks, and never share passwords or verification codes. Review the app’s privacy policy to understand what information may be collected and how it is used.
What should I do if I cannot log in or the app does not recognize my account?
First, check that you are using the correct login details and that your internet connection is working. Updating the app, restarting your device, or using the password-recovery option may resolve common problems. If your account is not eligible, your information has changed, or verification messages are not arriving, contact Aspire through its official support channels rather than relying on unofficial websites or third-party assistance.
Does Aspire Account Center require any special device permissions or fees?
The application may request permissions needed for functions such as notifications, secure verification, or access to basic device features. You can review and manage these permissions in your Android or iOS settings, although refusing some permissions may limit certain features. Downloading the app may be free, but account services, transactions, or other products accessed through it could have separate terms, charges, or eligibility requirements.


